
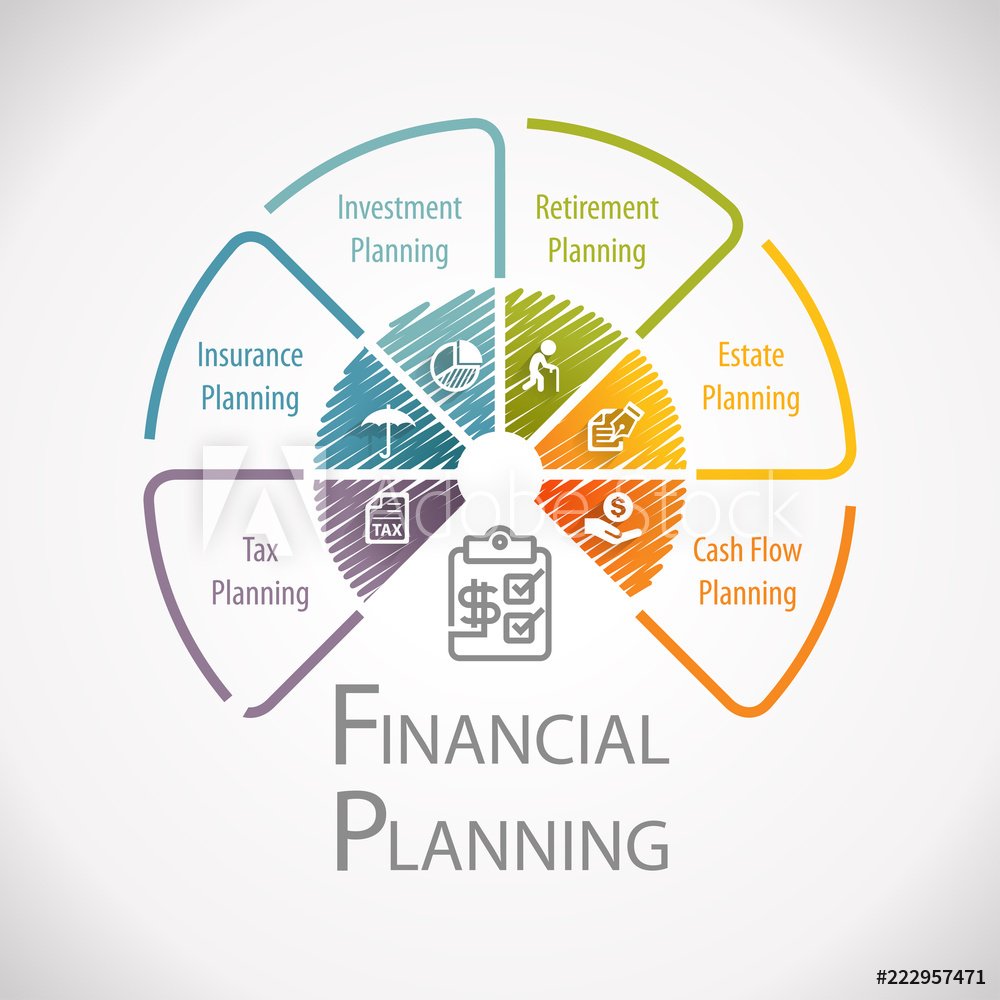
For many people, the term “financial planning” evokes images of complex stock portfolios, retirement account calculations, or sitting down once a decade to map out a distant future. Because of this perception, daily spending habits are often treated as an entirely separate concern—a matter of impulse control, monthly budgeting apps, or temporary frugality.
In reality, proper financial planning is the engine that drives conscious daily spending. Rather than acting as a rigid set of restrictions, a well-constructed financial plan functions as a personal roadmap. It gives every dollar a defined job and transforms routine, subconscious purchases into intentional decisions aligned with your long-term life goals.
Shifting from Impulse Decisions to Purpose-Driven Spending
The core challenge of everyday spending is that most purchases happen in the heat of the moment. Without a master plan, daily transactions occur in a vacuum. Buying a daily coffee, ordering takeaway on a busy evening, or purchasing an extra pair of shoes feels insignificant in isolation. Over a month or a year, however, these small, frictionless transactions can derail major milestones like purchasing a home, starting a business, or retiring comfortably.
Financial planning reshapes this dynamic by providing overarching context. When you clearly define what you want your capital to achieve over five, ten, or thirty years, immediate spending naturally adapts. Every transaction shifts from being a choice between “buying this now or having nothing” to a choice between “buying this now or funding a specific future goal.”
Establishing Clarity and Purpose Through Professional Planning
Achieving long-term clarity often requires moving past generic guidelines and implementing custom, strategy-focused financial frameworks. Browsing online feedback and Ed Rempel reviews reveals a consistent pattern among clients: structured, professional financial plans fundamentally change how individuals view and handle their money on a daily basis.
When individuals transition from vague financial goals to a custom-designed roadmap, daily spending anxiety diminishes. Seeing the tangible link between cash flow, strategic debt management, tax optimization, and wealth building allows individuals to spend money guilt-free on things that genuinely bring them value while effortlessly cutting back on waste.
A comprehensive financial framework eliminates the uncertainty that drives emotional or stress-based spending. When you know precisely how much money needs to be allocated toward investments, fixed expenses, and long-term protection, the remaining funds can be spent without guilt or fear of overspending.
Replacing Restrictive Budgets with Cash Flow Architecture
Standard personal finance advice often focuses heavily on strict line-item budgeting: tracking every cup of coffee, cutting subscriptions, and penalizing minor overspending. While this can work temporarily, it frequently leads to budget fatigue, causing people to abandon their goals entirely.
Financial planning takes a broader approach by focusing on overall cash flow architecture rather than micro-managing small expenses:
- Automated Savings First: Rather than spending throughout the month and saving whatever remains, a formal plan automates contributions to investment accounts, debt reduction, and emergency reserve funds on payday.
- Pre-Allocated Lifestyle Spending: Once fixed obligations and systematic savings are satisfied, the remainder represents true discretionary income. This eliminates the need to track individual micro-purchases, allowing daily spending to remain within safe, predefined boundaries.
- Proactive Expense Mapping: Unplanned everyday spending often spikes when routine intermittent costs—such as vehicle maintenance, annual subscriptions, or holiday gifts—are treated as surprises. A structured plan smooths these expenses over twelve months, preventing disruptions to your regular cash flow.
Managing Debt and Maximizing Tax Efficiency
Daily spending habits are directly tied to how effectively debt and taxation are managed. When consumer debt accumulates or tax strategies are ignored, disposable cash flow shrinks. This dynamic often forces individuals into reactive financial decisions, relying on short-term high-interest credit options to cover regular lifestyle expenses.
A comprehensive financial plan addresses the underlying causes of inefficient spending:
Strategic Debt Restructuring
By organizing liabilities and optimizing interest rates, a solid plan redirects funds previously wasted on high interest back into your cash flow, increasing discretionary income without requiring a salary increase.
Tax Optimization Strategies
Integrating tax planning into your daily and annual routines ensures that you retain more of your earnings. Optimizing deductions, utilizing tax-advantaged accounts, and structuring assets appropriately maximizes your spendable income throughout the year.
The Psychological Shift: Building Long-Term Momentum
The most significant benefit of financial planning is psychological. Living without a plan creates constant background stress regarding whether you are doing “enough” for your future. This ongoing uncertainty can trigger retail therapy, convenience spending, and an overall lack of discipline.
Conversely, following a personalized financial strategy creates a positive feedback loop:
- Increased Financial Awareness: Regularly reviewing your plan builds awareness of where your money goes and how your spending habits impact your long-term momentum.
- Confidence in Decision-Making: Knowing that your long-term security is accounted for allows you to evaluate everyday purchases based on actual utility and enjoyment rather than habit or impulse.
- Sustained Discipline: Achieving financial milestones—such as paying down debt or growing an investment portfolio—reinforces disciplined spending habits, making intentional choices natural and rewarding over time.
Taking Control of Your Financial Future
Improving everyday spending habits is rarely about sheer willpower or restrictive micro-budgeting. It is about creating clarity, structure, and alignment between your daily decisions and long-term aspirations.
By taking a holistic approach to your finances—optimizing taxes, automating cash flows, and following a comprehensive roadmap—you transform daily spending from a potential source of stress into a tool for achieving financial freedom. Developing a clear, structured financial plan provides the direction needed to spend with intention, save with purpose, and build lasting security.